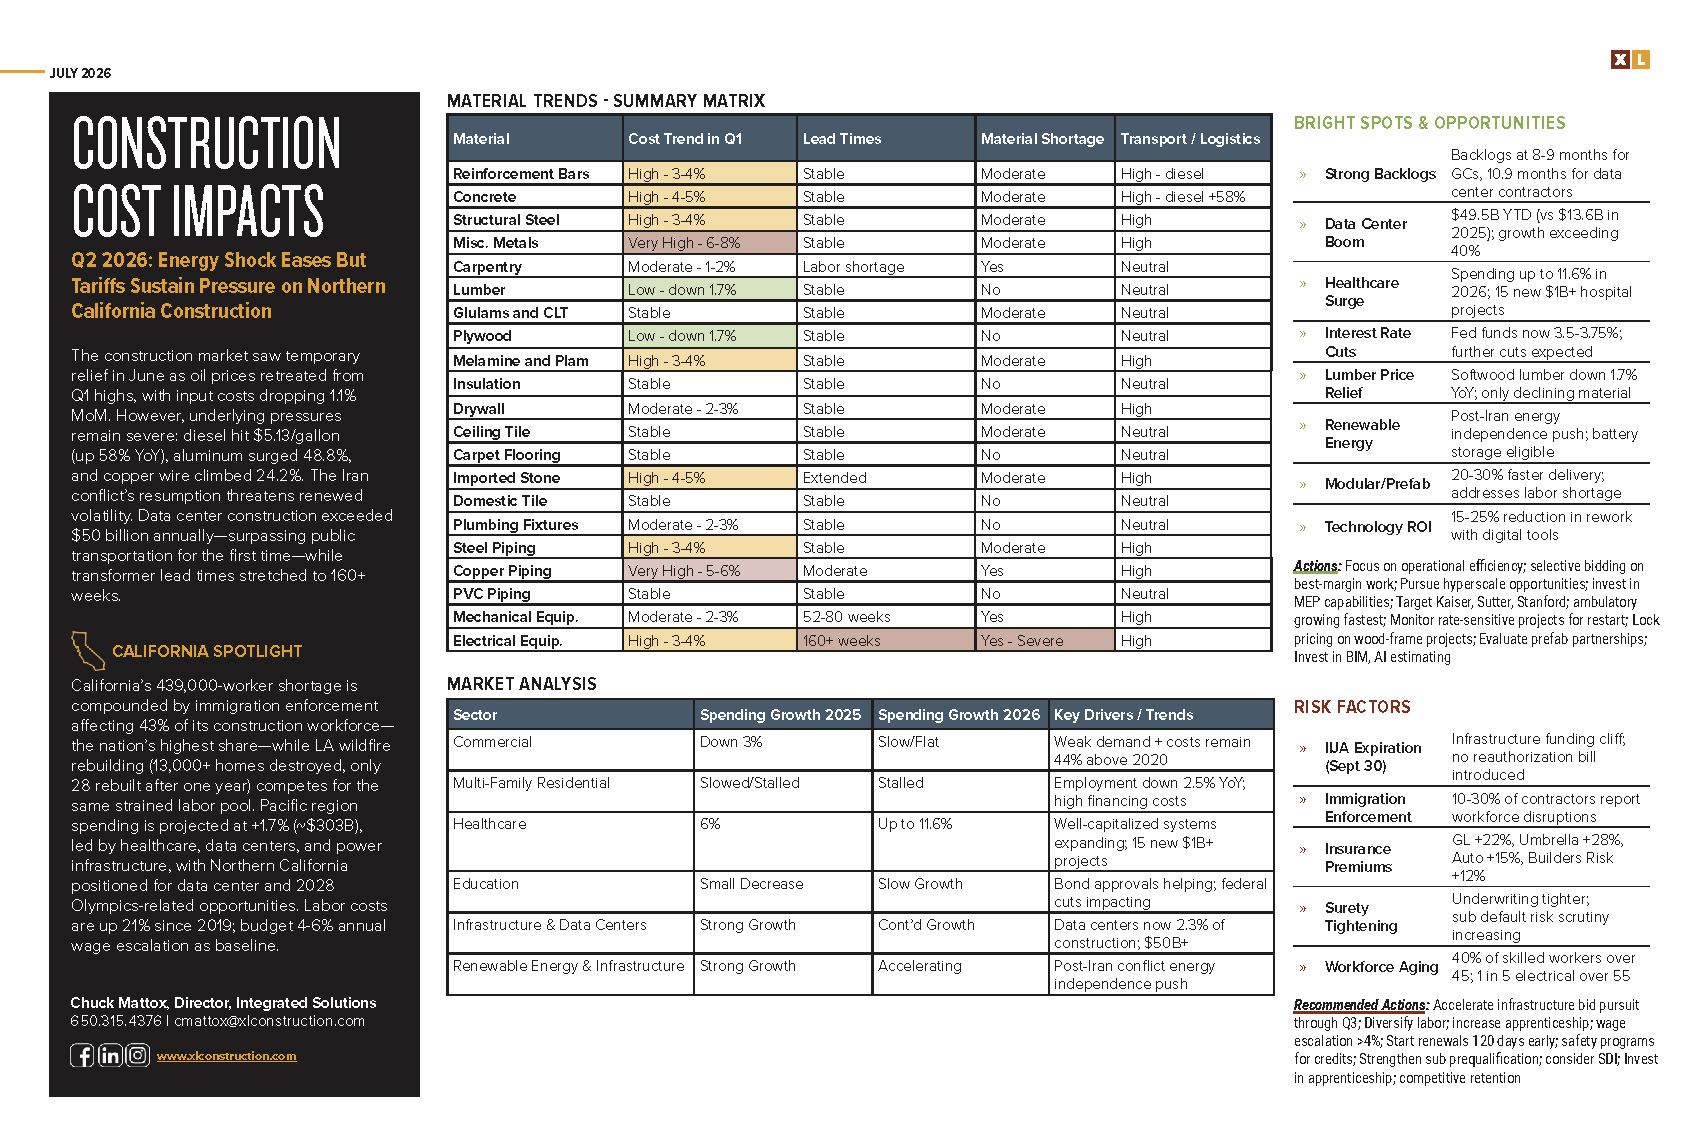
The construction market saw temporary relief in June as oil prices retreated from Q1 highs, with input costs dropping 1.1% MoM. However, underlying pressures remain severe: diesel hit $5.13/gallon (up 58% YoY), aluminum surged 48.8%, and copper wire climbed 24.2%. The Iran conflict’s resumption threatens renewed volatility. Data center construction exceeded $50 billion annually—surpassing public transportation for the first time—while transformer lead times stretched to 160+ weeks.
California Spotlight
California’s 439,000-worker shortage is compounded by immigration enforcement affecting 43% of its construction workforce— the nation’s highest share—while LA wildfire rebuilding (13,000+ homes destroyed, only 28 rebuilt after one year) competes for the same strained labor pool. Pacific region spending is projected at +1.7% (~$303B), led by healthcare, data centers, and power infrastructure, with Northern California positioned for data center and 2028 Olympics-related opportunities. Labor costs are up 21% since 2019; budget 4-6% annual wage escalation as baseline.
BRIGHT SPOTS & OPPORTUNITIES
- Strong Backlogs: Backlogs at 8-9 months for GCs, 10.9 months for data center contractors
- Data Center Boom: $49.5B YTD (vs $13.6B in 2025); growth exceeding 40%
- Healthcare Surge: Spending up to 11.6% in 2026; 15 new $1B+ hospital projects
- Interest Rate Cuts: Fed funds now 3.5-3.75%; further cuts expected
- Lumber Price Relief: Softwood lumber down 1.7% YoY; only declining material
- Renewable Energy: Post-Iran energy independence push; battery storage eligible
- Modular/Prefab: 20-30% faster delivery; addresses labor shortage
- Technology ROI: 15-25% reduction in rework with digital tools
- Actions: Focus on operational efficiency; selective bidding on best-margin work; Pursue hyperscale opportunities; invest in MEP capabilities; Target Kaiser, Sutter, Stanford; ambulatory growing fastest; Monitor rate-sensitive projects for restart; Lock pricing on wood-frame projects; Evaluate prefab partnerships; Invest in BIM, AI estimating
RISK FACTORS
- IIJA Expiration (Sept 30): Infrastructure funding cliff; no reauthorization bill introduced
- Immigration Enforcement: 10-30% of contractors report workforce disruptions
- Insurance Premiums: GL +22%, Umbrella +28%, Auto +15%, Builders Risk +12%
- Surety Tightening: Underwriting tighter; sub default risk scrutiny increasing
- Workforce Aging: 40% of skilled workers over 45; 1 in 5 electrical over 55
- Recommended Actions: Accelerate infrastructure bid pursuit through Q3; Diversify labor; increase apprenticeship; wage escalation >4%; Start renewals 120 days early; safety programs for credits; Strengthen sub prequalification; consider SDI; Invest in apprenticeship; competitive retention
Read the full report here: XLC_Construction Cost Impacts_July 2026